
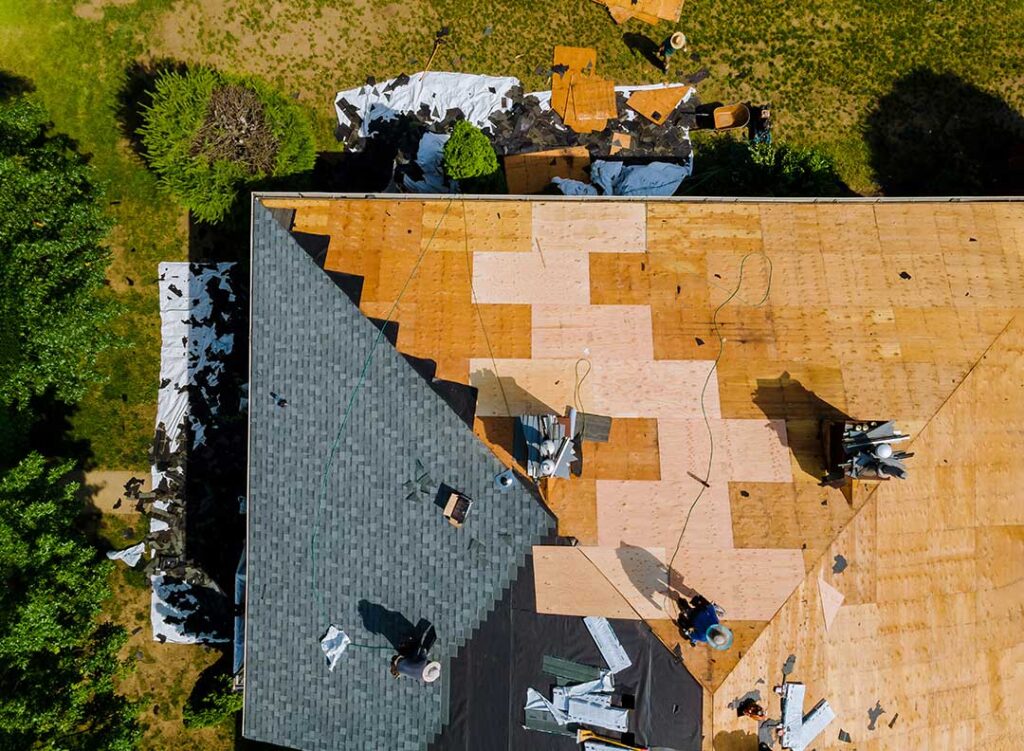
Roof damage can be difficult to document, especially after heavy snow, wind, ice, or falling branches. The goal is to create a clear record showing what happened, what was damaged, what temporary steps were necessary, and what expenses followed.
For residents of Altamont, NY, seasonal weather can produce several different roof-related problems, including missing shingles, lifted flashing, ice-related leaks, fallen limbs, damaged gutters, and water stains that appear inside days after a storm. Good documentation does not guarantee coverage, but it can make the claim easier to evaluate.
What should be done first after roof damage?
Safety comes before photographs. Do not climb onto a steep, wet, icy, or visibly unstable roof. From the ground, take exterior photographs from several angles. Inside the home, avoid areas with sagging ceilings, exposed wiring, active leaks near electrical fixtures, or other hazards.
If water is entering the home, take reasonable temporary steps to limit additional damage. This might include placing containers under a leak, moving furniture, covering belongings, or using a temporary tarp when it can be done safely. New York’s Department of Financial Services advises policyholders to document damage before cleaning up and to make necessary immediate repairs to protect health and safety. ([dfs.ny.gov](https://www.dfs.ny.gov/consumers/disaster_flood?utm_source=openai))
Do not make permanent repairs or discard damaged materials before the insurer has had a reasonable opportunity to inspect them, unless leaving them in place creates a safety risk or would cause more damage.
Which photographs are most useful?
The strongest photo record combines wide views, medium-distance views, and close-ups. A close-up of one torn shingle may show the defect, but a wider photograph helps establish where that damage is located.
Photograph:
- The entire roofline and each roof slope visible from the ground
- Missing, cracked, lifted, curled, or displaced shingles
- Damaged flashing around chimneys, vents, skylights, and roof edges
- Dented gutters, downspouts, siding, trim, windows, or exterior equipment
- Fallen branches, detached objects, or other visible causes of impact
- Interior ceilings, walls, insulation, flooring, and personal belongings affected by water
- Water paths, stains, bubbling paint, or sections of drywall that had to be opened
- Temporary protective measures, such as tarps or containers
- Areas that were not damaged, when they help show the overall condition of the property
Take photographs before moving objects or cleaning up whenever possible. Use a ruler, tape measure, or familiar object for scale in close-up photographs. Keep the original files rather than relying only on edited or compressed versions.
A short video can add useful context. Slowly record the exterior, interior rooms, active dripping, and the location of damaged items. Speak the date, room, and observation into the recording if helpful. New York guidance recognizes photographs and video as reasonable forms of proof in disaster-related claims, depending on the circumstances and policy requirements. ([dfs.ny.gov](https://www.dfs.ny.gov/consumers/disaster_flood?utm_source=openai))
How can the timing and cause be documented?
Write down when the damage was first noticed and what weather conditions occurred beforehand. Useful details may include:
- The date and approximate time of the storm or event
- Strong wind, heavy snow, ice buildup, hail, or falling limbs
- Whether the roof had been leaking before the event
- When water was first observed indoors
- Which rooms were affected
- Whether the damage became worse over time
- Any emergency steps taken immediately afterward
Avoid guessing about the technical cause. A homeowner can describe what was observed without stating that a particular event definitely caused every defect. For example, “water appeared on the upstairs ceiling after strong wind and rain” is more useful and cautious than making an unsupported conclusion about the roof’s construction or age.
Weather records, dated phone photographs, prior maintenance records, inspection reports, and receipts for earlier roof work may help establish the roof’s condition before the loss. They can also help distinguish new damage from older wear, although the insurer—not the homeowner’s photographs alone—determines how the policy applies.
What paperwork should accompany the claim?
Create a simple claim file, either digitally or on paper. Include:
- The policy number and declarations page
- A written description of what occurred
- A room-by-room list of damage
- Photographs and videos labeled by date and location
- Receipts for emergency materials, cleanup, temporary lodging, or other related costs
- Invoices, receipts, or records showing the age and purchase price of damaged belongings
- Estimates or written descriptions of necessary repairs, if available
- Notes from calls, inspections, and conversations with the insurer or adjuster
The New York Department of Financial Services recommends keeping records of conversations, including names, dates, and times, and following up important verbal discussions in writing. It also advises providing requested inventories, receipts, credit-card statements, and other documents that help establish property value. ([dfs.ny.gov](https://www.dfs.ny.gov/consumers/disaster_flood?utm_source=openai))
Keep copies of everything submitted. Organize files by category, such as “exterior,” “interior,” “contents,” “expenses,” and “communications.” Use filenames that identify the subject, such as `kitchen_ceiling_2026-09-16.jpg`, rather than leaving files with generic camera numbers.
How should damaged belongings be listed?
A room-by-room inventory is usually clearer than a single total. For each damaged item, record:
- Item description and brand or model, if known
- Approximate purchase date
- Original cost or estimated replacement cost
- Current condition
- Whether the item can be repaired, cleaned, or must be replaced
- Supporting receipt, photograph, warranty, or account record
Photograph damaged belongings in place before discarding them. If an item must be removed because of mold, contamination, a safety concern, or severe water damage, photograph it thoroughly and keep a small material sample when practical and safe. The National Association of Insurance Commissioners recommends documenting household contents by room and retaining purchase information when available. ([content.naic.org](https://content.naic.org/article/what-you-need-know-when-filing-homeowners-claim?utm_source=openai))
Do not assume that every item affected by a roof leak is covered. Coverage can depend on the source of the loss, exclusions, limits, deductibles, endorsements, depreciation rules, and whether the damage resulted from a covered event or long-term maintenance conditions.
What should be done before an adjuster visits?
Leave visible damage in its current condition when reasonably possible. If temporary repairs were necessary, photograph the area before and after the work. Save removed shingles, flashing, ceiling materials, or other components if doing so does not create a hazard or interfere with sanitation.
Prepare a short timeline and point out every affected area, including damage that is not obvious from the street. An adjuster may inspect the roof, attic, ceilings, insulation, walls, contents, gutters, and nearby structures. Do not assume that a visible ceiling stain represents the full extent of the loss, but do not expand the claim with unrelated or unsupported damage either.
A repair estimate may be useful for comparison, but an estimate is not the same as a coverage decision. The policy language and the insurer’s investigation control how the claim is handled.
What if the claim is disputed or the damage is found later?
Notify the insurer promptly if additional damage appears after the initial report. Keep documenting new discoveries with dates and photographs, and explain why the damage was not visible earlier.
Read the insurer’s written determination carefully. Check whether the disagreement concerns the cause of loss, the amount of damage, depreciation, the deductible, or a policy exclusion. Those are different issues and require different documentation.
New York policyholders can review guidance from the Department of Financial Services and keep a complete record of the claim. If a dispute remains unresolved, the agency provides consumer information about insurance complaints and claim-related assistance. ([dfs.ny.gov](https://www.dfs.ny.gov/consumers/disaster_flood?utm_source=openai))
The most useful documentation is timely, organized, and factual: show the condition before cleanup, describe what happened without speculation, preserve receipts and damaged materials when safe, and maintain a written record from the first report through the final claim decision.
